CSRD after Omnibus I: are you still in scope?
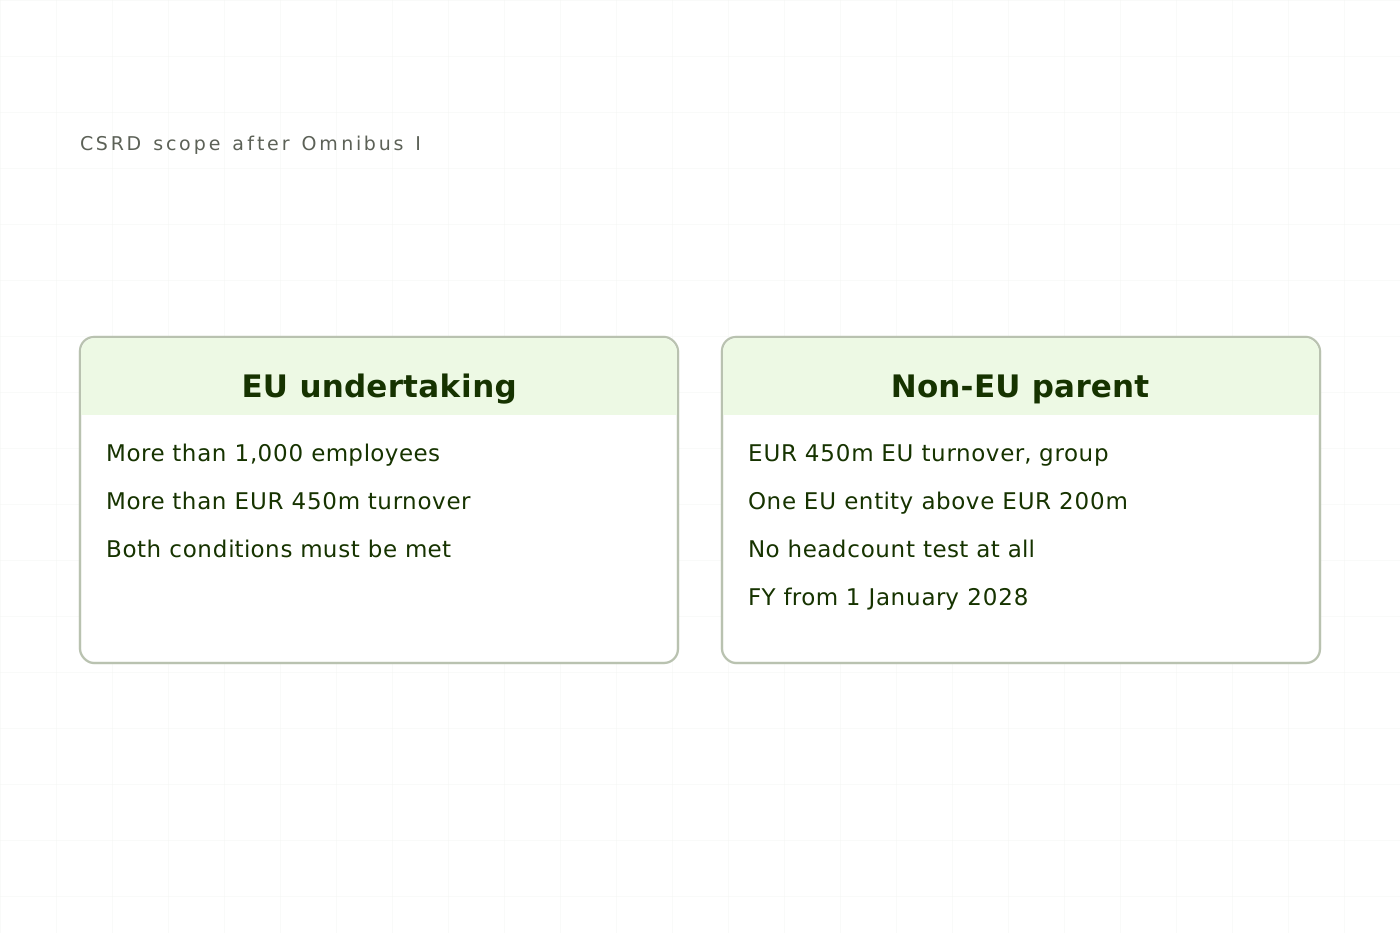
There is one question a Canadian or American group has to settle before it spends anything on European sustainability reporting, and the answer moved on 18 March 2026, when Directive (EU) 2026/470 of 24 February 2026, the Omnibus I Directive, entered into force. Every number in the scope test changed. The population of non-EU companies the directive reaches fell by roughly 88 percent, from about 10,000 to about 1,200, which means a scoping memo written in 2024 is now evidence of very little either way.
That works in both directions: groups that were told they were caught may not be. Groups that stopped reading when the simplification package was announced may still clear the new trigger, because the non-EU test is not a scaled-up version of the old one; it runs on different inputs. You can work it in an afternoon with two figures out of your consolidation pack.
One boundary before the numbers. This article covers the scope arithmetic and the timing, both of which are confirmed. It does not describe what you would have to disclose if you are in scope, because the ESRS themselves were amended after this article was first written: Commission Delegated Regulation (EU) 2026/1563 was published in the Official Journal on 21 September 2026, enters into force on 10 November 2026 and applies to financial years beginning on or after 1 January 2027, with financial year 2026 reporters choosing a version and stating which, as checked on 29 September 2026. No primary text gives a datapoint count for the amended standards, and guessing at datapoint counts is how scoping memos turn into wasted quarters.
Free
Read every article, in full.
- Every article on the site, start to finish
- Sources cited and linked on all of them
- New pieces on Intelex configuration and EHS practice
Would rather not sign up? Email me and I will send it over.