CSDS 1 and 2 are voluntary. They are not ignorable.
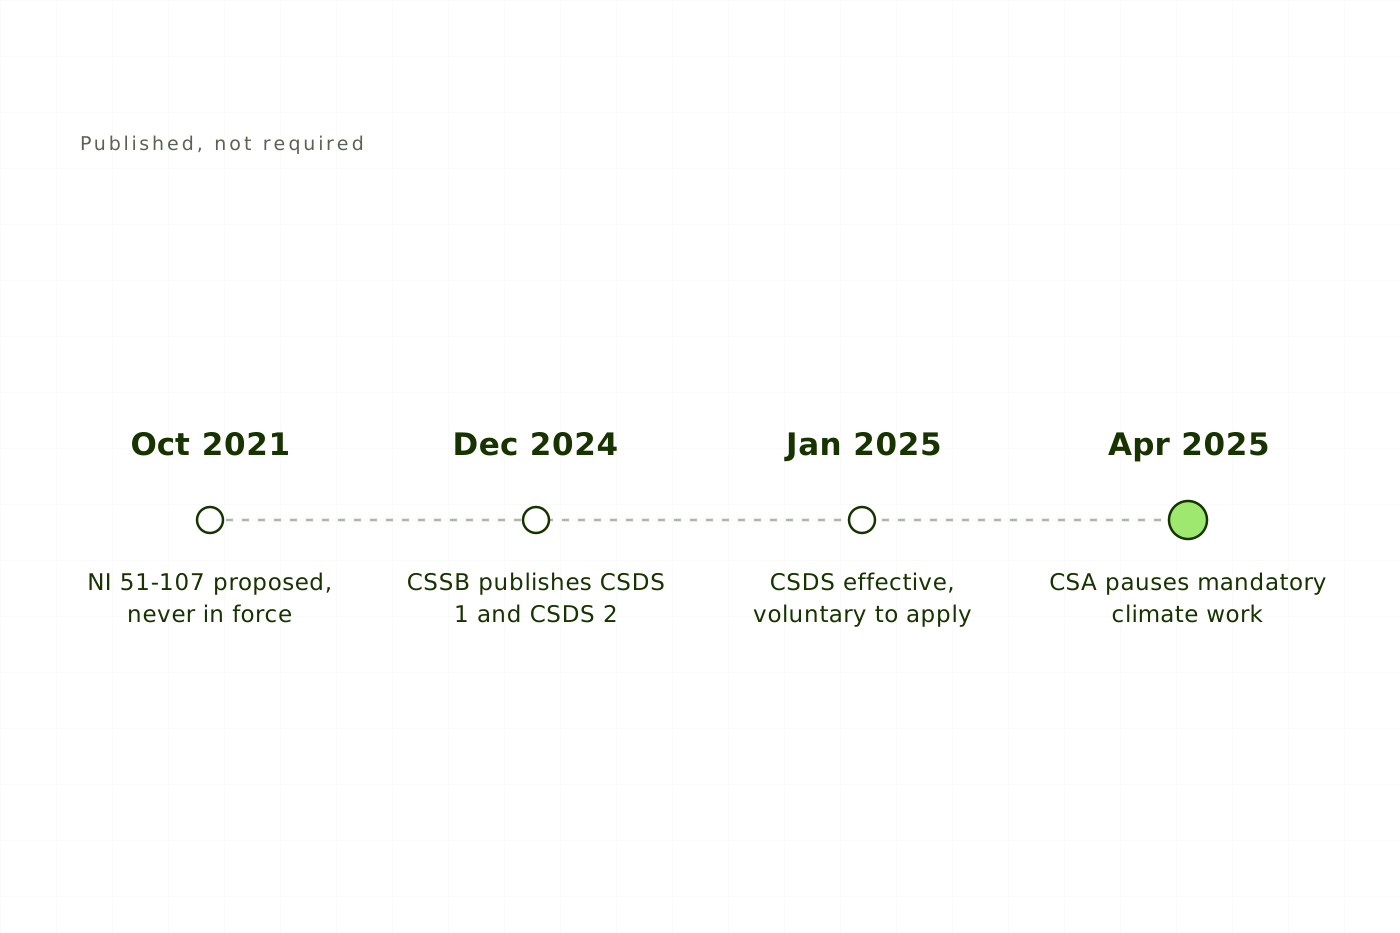
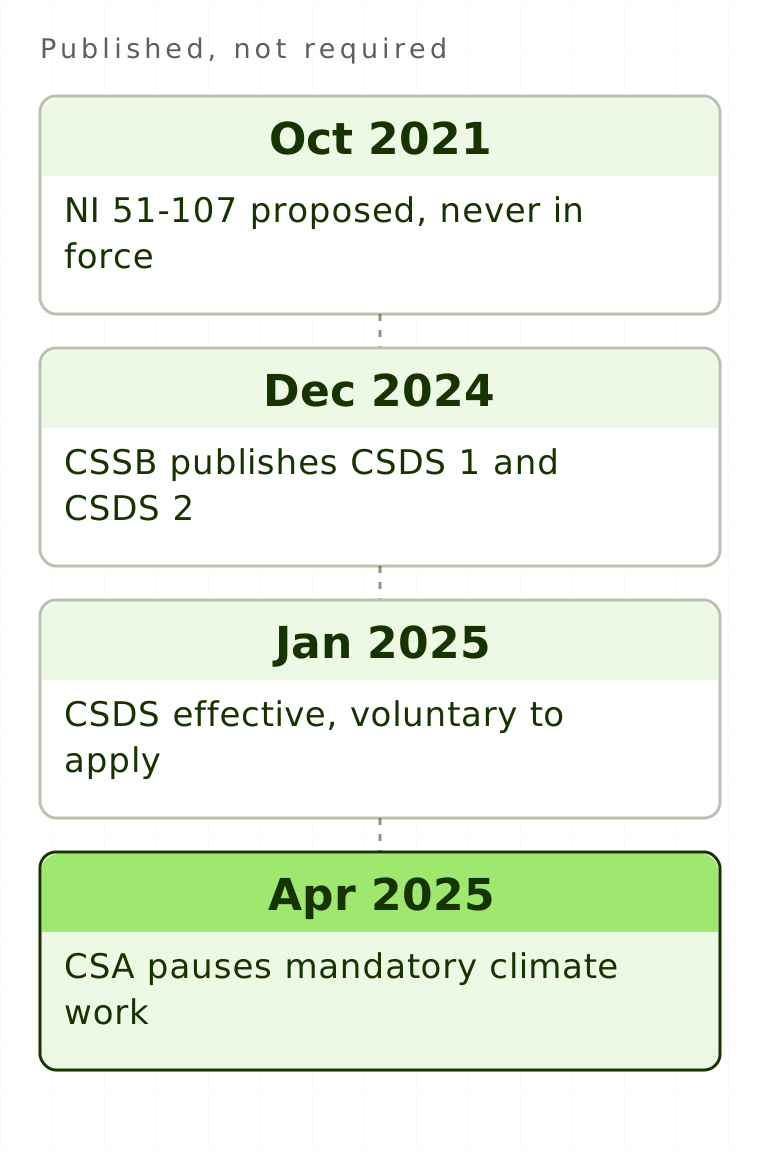
Ask whether your Canadian company has to report under CSDS 1 and CSDS 2 and the answer is short. It does not. The Canadian Sustainability Standards Board published both standards on 18 December 2024, effective for annual reporting periods beginning on or after 1 January 2025, and aligned them to the ISSB standards IFRS S1 and S2 with Canadian modifications. The CSSB writes standards. It cannot require anyone to apply them.
The two bodies that can are the Canadian Securities Administrators and OSFI. The CSA paused its mandatory climate disclosure work on 23 April 2025, and that pause was still in effect as at August 2026. NI 51-107, the instrument that would have carried the requirement, was proposed on 18 October 2021 and has never been brought into force. The CSA has said it will revisit the file in future years and will consider feedback from the CSSB consultation. No date has been attached to that.
So the legal position is settled and comfortable. The operational position is not, and the difference between them is what this article is about.
Free
Read every article, in full.
- Every article on the site, start to finish
- Sources cited and linked on all of them
- New pieces on Intelex configuration and EHS practice
Would rather not sign up? Email me and I will send it over.